


“I wanted to know how I would retire, how much I could expect, whether I’d made good enough plans for my retirement.”
When Louise came to Reeves at 53, she had recently become aware of changes to pension legislation around how pensions could be taken, and it prompted some important questions about her own retirement.
She had built up 10 pension arrangements over her working life and was approaching the point where she needed to start thinking seriously about how they would provide an income in retirement. What she really wanted to understand was how she should use them. She had mainly encountered annuities during her working life and had several existing arrangements, while drawdown was something she knew very little about.
Her starting point
At 53, Louise had 10 pension arrangements: eight defined contribution pensions and two defined benefit pensions. She wanted to achieve an income of around £2,250 a month from age 65, while also taking £10,000 from her pension to fund a bathroom renovation.
Understanding what her retirement could look like
We started by looking at Louise’s existing position and creating a cash-flow forecast to show how her plans could develop over time.
Using assumptions of 2% inflation and investment returns of 4 to 5%, the initial forecast showed that her existing arrangements were not quite going to provide the retirement she wanted. If nothing changed, the initial forecast indicated that Louise’s cash assets would run out, leaving a projected shortfall of £45,748 by age 90.
The graph focused on her cash assets and did not include income from her defined benefit pensions or State Pension. However, our analysis showed that these sources alone would not provide enough income to meet the retirement income Louise wanted.
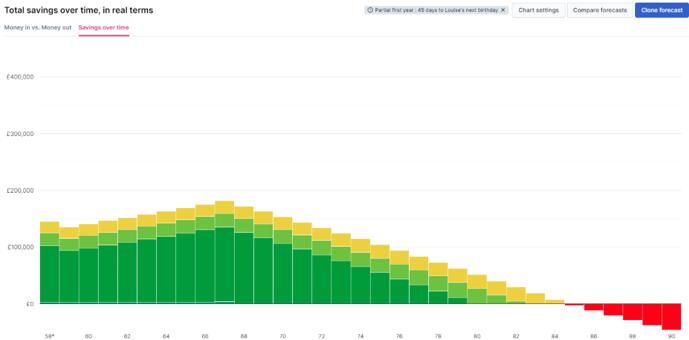
This gave Louise a clearer picture of the challenge, but it also allowed us to look beyond simply whether she had enough money. We could explore how her different pensions could work together, and importantly, how she could use them to create the retirement income she wanted.
Understanding her options
The advice was not simply about choosing between different pension products. It was about understanding Louise’s circumstances and looking at the options available to her.
Her two defined benefit pensions were reviewed by a specialist, who recommended that she keep them where they were.
We then looked more closely at her eight defined contribution pensions. These were not being actively managed, offered a limited range of investment options and were underperforming based on industry benchmarks. After reviewing the guarantees and benefits of each scheme, we recommended consolidating the defined contribution pensions into one.
Alongside this, we modelled a phased retirement income of £2,500 a month until age 75, followed by £2,000 a month thereafter.
For Louise, an important part of the process was understanding what this meant in practice. She had come to Reeves knowing about annuities, but drawdown was new to her. Advice gave her the opportunity to understand not just where her pensions were invested, but how they could be used to provide an income throughout retirement.
“Coming to Reeves did two things: first of all it helped me to understand about consolidation, but secondly I’ve learned about drawdown, which I knew nothing about.”
Hear Louise’s experience
In her own words, Louise explains what she wanted to understand when she first came to Reeves, how the advice changed her understanding of her pension options, and why she continues to value having someone to talk to as she approaches retirement.
A plan she could understand
The revised plan produced a very different projected outcome. Louise’s initial projected deficit of £45,748 became a projected surplus of £15,258, an improvement of £61,006 in her forecast position.
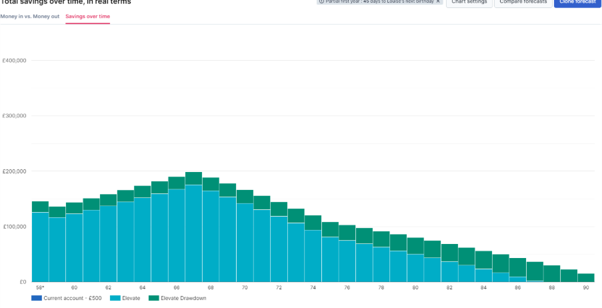
The numbers gave Louise greater confidence in her retirement plans, but the value of the advice went beyond the forecast itself. She now had a much clearer understanding of the choices available to her and how her pension arrangements could support the retirement she wanted.
She was also able to take the £10,000 she had wanted for her bathroom renovation while continuing with her longer-term retirement plan.
Want to see how Louise’s numbers worked in practice? Reeves has also created a webinar walking through her case, including the different pension arrangements, the cash-flow forecast and the approach to her retirement income.
Where she is now
Louise has continued to work with Reeves as she approaches retirement. Regular reviews give her the opportunity to revisit her plans, talk through changes and understand whether anything needs to be adjusted.
For Louise, that ongoing relationship is an important part of retirement planning. Her circumstances and the wider environment can change, and she values having someone who understands her plans and can help her make sense of what those changes mean for her.
Ultimately, what she says she has found in Reeves is a partner to work through those decisions with her.
“I feel like Reeves are partners in my pension, in my road to a successful pension retirement.”