


“With the guidance and support of Reeves, I was able to retire at the age of 56. That’s nine years earlier than I had initially hoped for.”
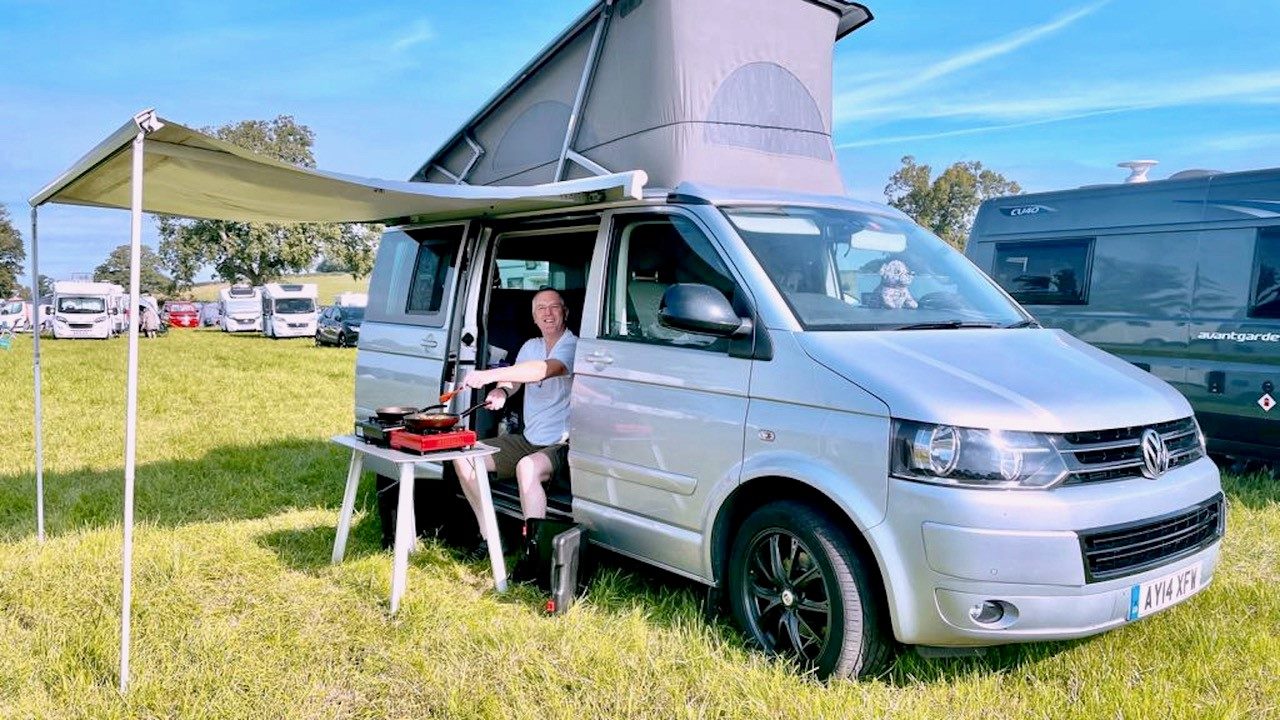
For years, Jim Kelly had a clear picture of what he wanted retirement to look like. After a long career in the automotive manufacturing industry, he and his wife dreamed of travelling in a camper van, exploring new places and making the most of their time together while they were still fit and active.
Initially, Jim expected to work until he was 65. He had no idea that retiring earlier might be possible, but he had spent decades building up his pensions and investments and wanted to understand what they could realistically provide.
Jim has been a Reeves client for more than 25 years, with regular advice helping him manage his pensions and investments as his working life evolved. Over time, his retirement plan developed, and the prospect of finishing work earlier began to look increasingly achievable.
With a clearer understanding of his finances, a considered investment strategy and careful planning around how he would draw an income, Jim was able to bring retirement forward and start living the life he had imagined.
Turning a Retirement Dream into a Plan
Jim’s relationship with Reeves began much earlier, when he had recently married, bought his first home with his wife and was preparing to welcome their first child. With new responsibilities and a better-paid job, he wanted to get his finances in order and plan for the future of his growing family.
An initial financial review helped him understand where he stood, from his income and outgoings to his pensions, debts and longer-term priorities. Reeves then developed a plan showing how regular saving and investment, supported by ongoing reviews, could help him work towards his goals.
As Jim changed employers over the years, Reeves continued to help him manage his pension arrangements and investments. His plan was reviewed as his circumstances changed, keeping his long-term ambitions in view rather than treating retirement as a decision to make at the last minute.
Eventually, Jim reached a point where early retirement was no longer just a distant aspiration. It was something he could explore in detail, with a financial plan to help him understand what might be possible.
Understanding the Numbers
When Jim wanted to examine his retirement options more closely, Reeves looked at his pensions, ISA savings, expected retirement income and investment assumptions to build a picture of how his finances might develop over time.
The initial forecast assumed annual inflation of 2% and an annual investment return of 5% before charges. Using the value of Jim’s assets at retirement, the modelling showed that his pensions and investments would not be sufficient to cover his desired retirement income throughout the forecast period. His funds were projected to run out at around age 80, leaving a shortfall of £109,753 against his planned income by age 90. This highlighted the need to review his pension arrangements, investment strategy and approach to drawing an income, to help make his early retirement ambitions achievable.
That was a significant gap between Jim’s existing position and the retirement he wanted. It showed why understanding the different pension options, how his investments were managed and how he would take money from his savings was so important.
Rather than treating the forecast as a fixed outcome, Reeves explored what could be changed to make his retirement plans more sustainable and give him greater flexibility.
Making His Pensions Work Together
A key part of the advice involved reviewing Jim’s defined benefit pension. This type of pension would normally provide a regular income, with increases over time, but Jim wanted to explore whether greater flexibility could better support his plans to retire early and make his pension wealth available to his family if he died with money remaining.
Because defined benefit pension transfers require specialist expertise, Reeves referred Jim to a pension transfer specialist who we work with from an external firm that has the permissions to look at DB pensions, to assess whether a transfer was suitable for his circumstances and objectives. Following a thorough assessment, the specialist recommended transferring the benefits into a money purchase pension.
The recommendation was specific to Jim’s circumstances. A defined benefit transfer is not right for everyone, which is why specialist assessment was an important part of the process.
Reeves also consolidated Jim’s three existing money purchase pensions into one arrangement, making his retirement savings easier to manage and giving him access to a wider range of investment options. His investments were aligned with his attitude to risk and retirement objectives, with the portfolio reviewed over time as markets and circumstances changed.
Whenever we look to do a consolidation exercise for our clients we review each scheme individually and assess charges, guarantees, safeguarded benefits, exit costs and investment options to determine if a move if the correct option for each pension.
The advice also considered how Jim could use his existing savings tax-efficiently. This included making a pension contribution from cash he did not need immediately, taking account of the available tax relief, and planning which savings to draw on at different stages.
Together, these decisions helped create a more joined-up retirement strategy, with attention paid not just to the value of Jim’s savings, but to how and when he could use them.
Building a More Sustainable Retirement
The final piece was working out how Jim could take an income without unnecessarily increasing his tax bill or drawing on the wrong assets at the wrong time.
The withdrawal strategy considered the income Jim expected to earn before retirement, the tax treatment of his pension and ISA savings, and how his money could be accessed once he stopped working. By planning withdrawals around his circumstances, Reeves could help him make better use of available allowances and understand how different sources of income fitted together.
The revised retirement forecast showed a substantial improvement. Using the assumptions in the webinar presentation, the projected shortfall of £109,753 became a projected surplus of £85,055 at age 90. That represented an improvement of £194,808 in the modelled position. Our after forecasts still include things like inflation, investment returns and of course we look at any tax that could be due.
These figures are projections rather than guarantees, and actual outcomes will depend on factors such as investment performance, inflation and future spending. However, the revised plan gave Jim a much stronger basis on which to make decisions about his retirement.
Most importantly, the planning helped turn the question from whether early retirement was realistic into how Jim could put it into practice.
Nine Years More to Enjoy Retirement
Jim’s own account of his journey is straightforward. He had originally expected to retire at 65, but he says the guidance and support he received from Reeves enabled him to retire at 56.
That gave him more time to enjoy the freedom he had been working towards. He and his wife could travel in their camper van, visit places they had always wanted to see and enjoy life while they were still active.
Since retiring, Jim has also made time for walking, cycling, concerts, photography and learning to play the guitar again. Having a budget and a clearer understanding of his finances helps him enjoy these experiences while keeping an eye on his longer-term position.
For Jim, early retirement was not simply about finishing work sooner. It was about having the freedom to spend his time differently, without losing sight of the need to manage his money carefully.
Advice That Continues into Retirement
Jim’s relationship with Reeves did not end when he stopped working. He continues to value regular communication, investment updates and the reassurance of knowing his pension arrangements are being monitored.
He recognises that investment markets change and that he is not an expert in managing his own portfolio. Having a team he trusts to explain what is happening, review his position and discuss any necessary changes gives him greater confidence in the decisions being made.
His experience also reflects the importance of starting to plan early, reviewing that plan regularly and adjusting it as life changes. Jim had spent many years working towards retirement, but it was the combination of long-term preparation and more detailed planning as retirement approached that helped bring his goal within reach.
For Jim, the result is more than a better-looking forecast. It is the opportunity to enjoy the retirement he had imagined, with more time for travel, family and the things he loves doing.
In the webinar, Jim shares more about his experience with Reeves, the decisions that helped him retire early and what he has been able to do since leaving work.